The Math of a 78% Drop: What the Dot-Com Crash Teaches Us About Money and Emotion
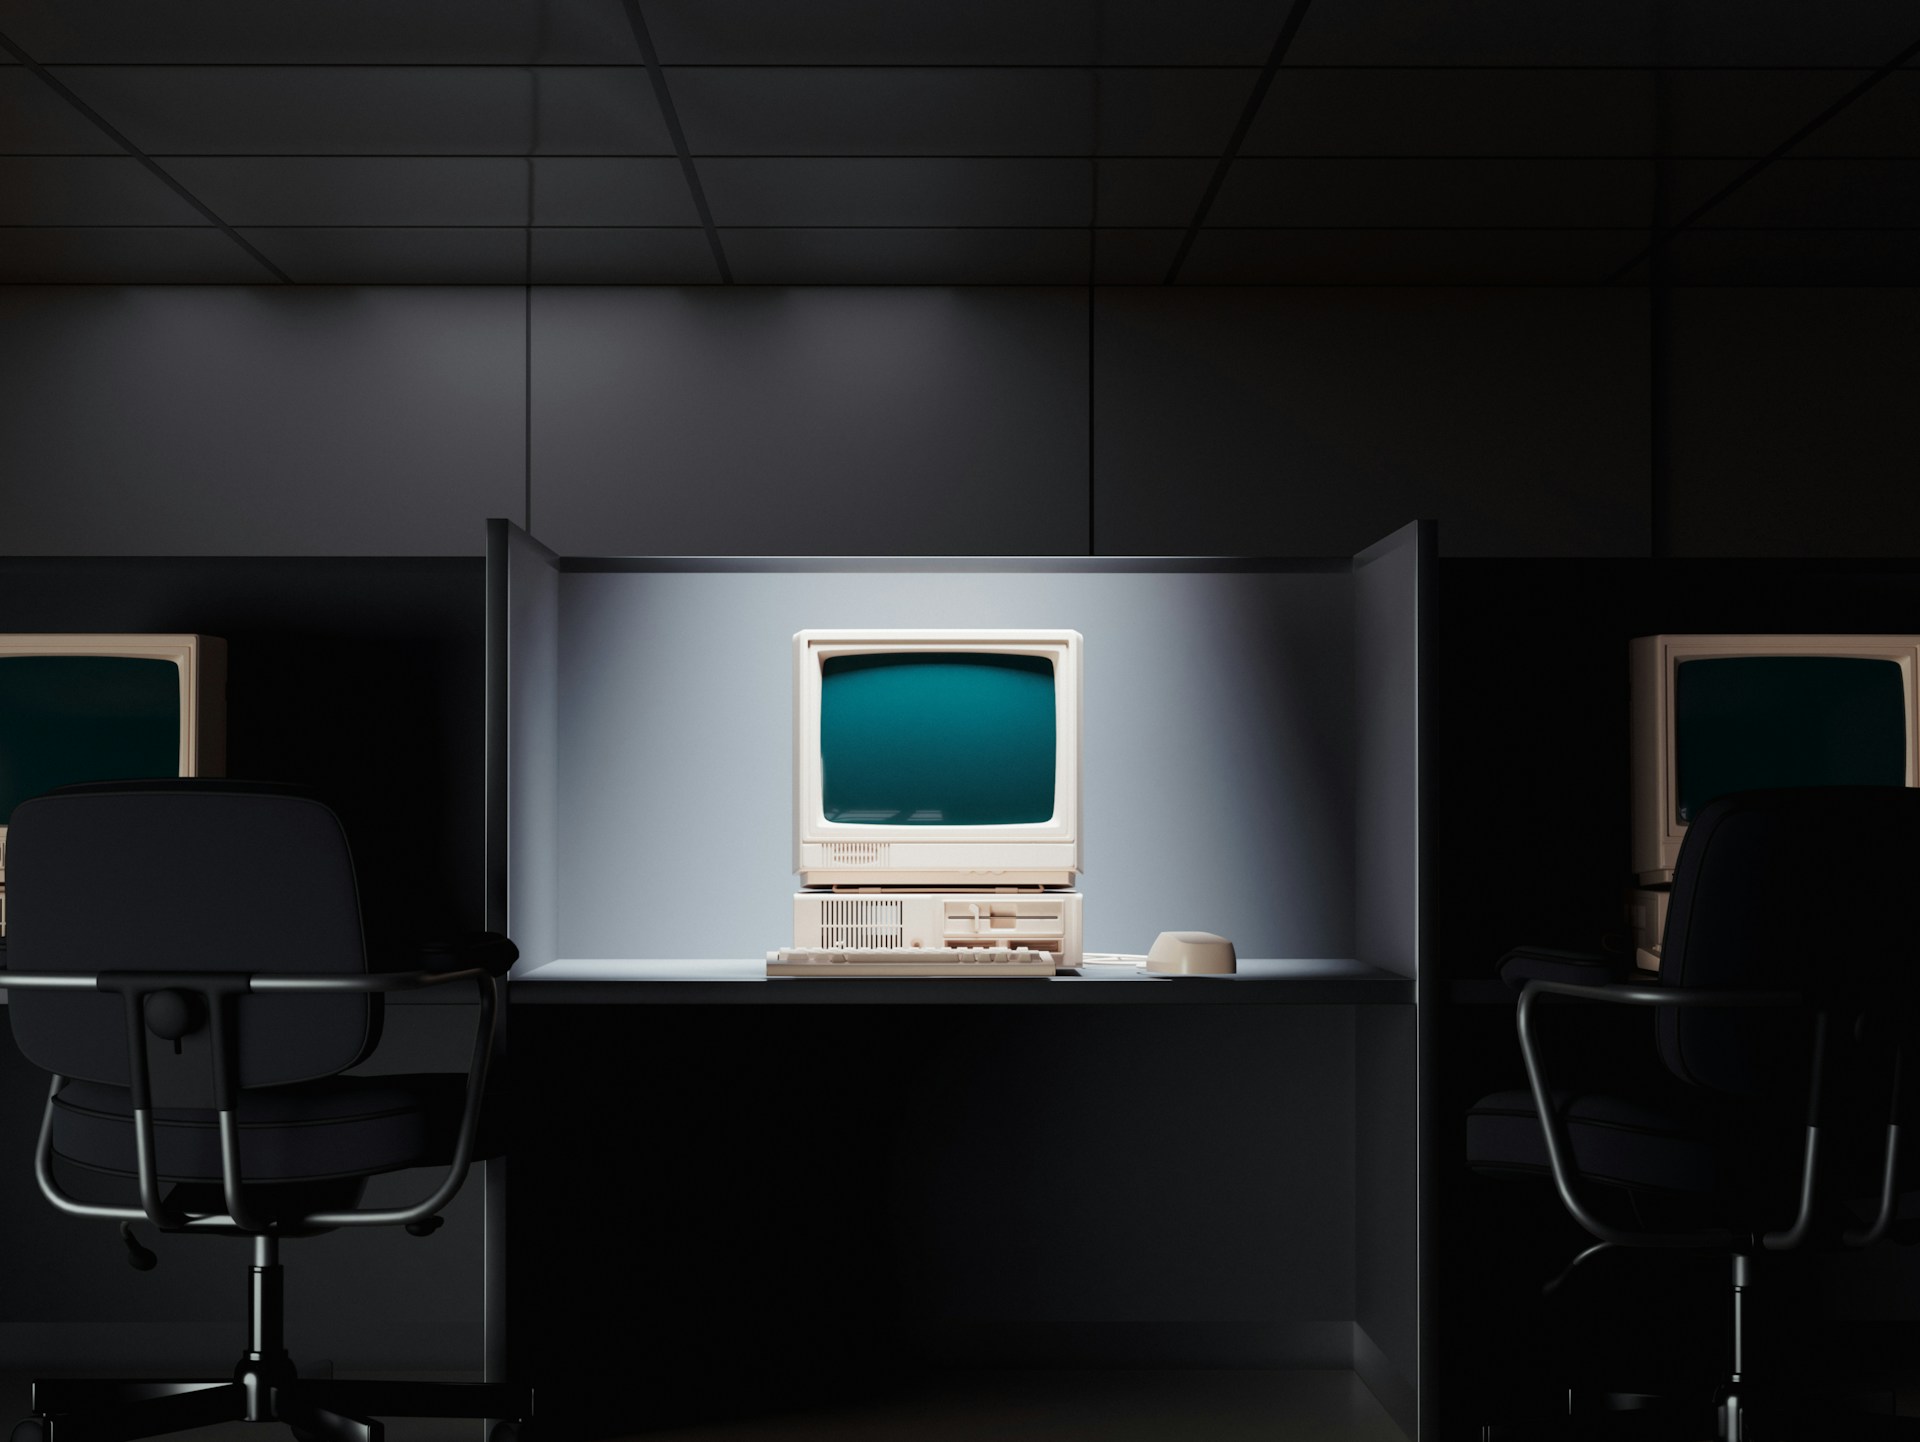
Some market moments are so dramatic that they become lessons for generations of investors. The dot-com crash is one of them. It’s a story about numbers, but it’s also a story about people, and what we tend to do when excitement turns to fear.
What happened
From its peak in March 2000 to its low in October 2002, the NASDAQ Composite, an index heavily weighted toward technology companies, fell by roughly 78%.
How did it get there? In the late 1990s, enthusiasm for the internet was running high, and for good reason: it really was changing the world. But excitement outran evidence. Investors poured money into internet startups, and many of those companies were valued on potential, website traffic, and growth stories rather than on profits or a clear path to earning them. Prices were being set by belief instead of by real-world business results.
A price built on a story is fragile. As cash ran low and companies struggled to show how their models would actually make money, confidence cracked, and prices followed. We call it a “bubble” now, but it’s worth remembering that it rarely feels like one from the inside.
Why down markets play tricks on the math
Here’s the part that surprises almost everyone: losses and gains aren’t symmetrical. When something falls, the gain needed to get back to even is always larger than the loss itself.
A 50% loss needs a 100% gain just to break even. A 78% loss needs a gain of roughly 355%. Let’s make that real.
Hypothetical example (for illustration only): Imagine an investor with $10,000 invested entirely in an investment that falls 78%. Their balance drops to $2,200. To get back to $10,000, that $2,200 would need to grow by $7,800, which is a gain of about 355%. This example is not based on any actual account or investment and does not reflect real results.
In the real world, the NASDAQ Composite’s price index did not climb back to its March 2000 level until 2015, roughly 15 years after the peak. That’s a long time to wait, and a reminder that the deeper the fall, the longer the road back.
It’s also worth noting that the NASDAQ was heavily concentrated in technology. An investor with a diversified portfolio, spread across asset classes, industries, and regions, would have had a different experience. Diversification can’t guarantee against loss, but it’s one of the tools designed to keep any single story from deciding your future.
Where the emotions come in
This is where behavioral finance earns its keep. The same human instincts show up on the way up and on the way down:
- On the way up: fear of missing out and herd behavior (“everyone is making money”), plus recency bias, the feeling that what’s been working will keep working.
- On the way down: loss aversion makes the pain of a drop feel enormous, which can push people to sell at exactly the wrong moment, or to freeze and avoid looking at all.
- On the way back: anchoring on a past price can lead people to hold on to an investment just to “get back to even,” even when it no longer fits their goals.
None of these make you a bad investor. They make you human. The goal isn’t to remove emotion from the process. It’s to make sure emotion isn’t the one in the driver’s seat.
Why a plan is your best navigation tool
No one can predict when the next downturn will come or how deep it will go, and no one should claim to. What you can do is build a plan that’s ready for one, a plan built around your goals, your timeline, and your comfort with risk rather than around the headlines.
In Accumulation, a plan keeps you contributing steadily and diversified, so a rough stretch is part of the journey rather than the end of it.
In Income & Preservation, a plan helps make sure the money you’ll need in the near term is set aside, so you’re not forced to sell investments during a decline.
In Legacy Planning, a plan keeps your bigger purpose in view: what you want your money to do, and for whom, long after any single market cycle.
Behavioral finance adds one more layer. Working with an advisor who understands the psychology of money can help you recognize your own tendencies before the stress hits, agree on guardrails in advance (like a cooling-off period before making big changes), and have someone in your corner to talk you through the rollercoaster. A plan made in a calm moment is a promise to your future self, and it’s easiest to keep when you don’t have to keep it alone.
Three questions to ask yourself
- If my portfolio dropped sharply tomorrow, would I know what my plan says to do?
- Is my money invested in a way that matches my goals and timeline, or in a way that just feels exciting right now?
- Who can I talk to before I make a big financial decision during a stressful time?
If you are interested in starting your plan or revisiting an already established plan, please reach out and we would be happy to walk through it with you.


Wondering If You're on the Right Track?
You don't have to figure it out alone. Schedule a complimentary conversation and get clarity on your next steps.